What is the market overview and scope of the Missiles And Missile Defense Systems Market?
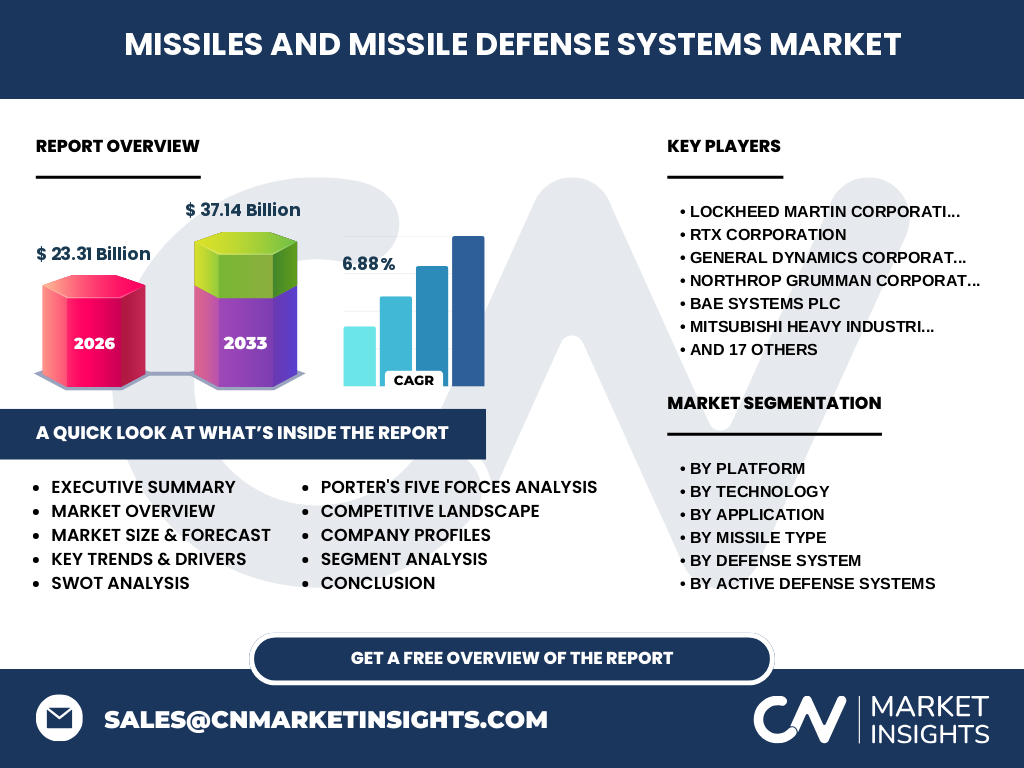
Our analysis indicates the Missiles And Missile Defense Systems Market represents a critical pillar of global defense expenditure, encompassing sophisticated kinetic interceptors, hypersonic deterrents, and networked shield architectures. Valued at 23.31 Billion in 2026, the sector is heavily governed by strict export control regimes such as ITAR and the Missile Technology Control Regime (MTCR), which heavily shape international procurement cycles and technological transfer limitations across allied defense ministries.
Key market drivers, restraints, challenges, and opportunities shaping Missiles And Missile Defense Systems Market
Structural demand is propelled by rising geopolitical friction and asymmetric aerial threats, driving massive investments in advanced propulsion systems and radar and tracking systems. However, severe regulatory export hurdles from bodies like the U.S. State Department and critical raw material supply bottlenecks for titanium and rare-earth magnets act as persistent constraints. Prime opportunities lie in modernizing legacy architectures with artificial intelligence and directed energy capabilities.
Emerging trends and growth patterns in Missiles And Missile Defense Systems Market
The sector is experiencing a radical shift toward hypersonic defense capabilities and software-defined command and control (C2) systems. Industry leaders like Lockheed Martin Corporation and RTX Corporation are aggressively pivoting toward open-architecture framework designs to ensure seamless interoperability between multi-domain platforms, drastically shrinking the sensor-to-shooter kill chain for complex ballistic and cruise missile engagements.
How did the COVID-19 pandemic impact the Missiles And Missile Defense Systems Market and drive recovery?
The pandemic introduced severe tier-2 and tier-3 supply chain disruptions, delaying critical assembly schedules for complex interceptor missile systems. Recovery has been robustly fueled by supplemental emergency defense appropriations from NATO member states. This post-pandemic surge has forced prime contractors to heavily diversify their sub-tier vendor bases, prioritizing domestic inventory resilience over pure just-in-time manufacturing efficiencies.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
Market concentration remains moderately high, dominated by aerospace primes such as Northrop Grumman Corporation, Boeing Defense Space & Security, and European heavyweights like MBDA Missile Systems and Thales Group. Strategic competition revolves around securing multi-year Department of Defense procurement contracts, investing in proprietary solid-fuel propulsion technologies, and establishing localized joint ventures to satisfy strict offset and indigenous manufacturing mandates.
Executive Summary of the Missiles And Missile Defense Systems Market
Our comprehensive research projects the Missiles And Missile Defense Systems Market to expand from 23.31 Billion in 2026 to 37.14 Billion by 2033, achieving a robust CAGR of 6.88%. Growth is primarily underpinned by escalating defense budgets in the Indo-Pacific and Eastern Europe, where military modernization priorities increasingly favor layered active defense shields over conventional deterrence models.
Market Forecast for Missiles And Missile Defense Systems Market (2027 to 2033)
Driven by compounding geopolitical instability and rapid technological evolution, our forecast shows the market scaling rapidly to reach 37.14 Billion by 2033 at a 6.88% CAGR. This trajectory will be heavily sustained by massive capital allocations toward advanced directed energy systems (Laser/HPM) and resilient space-based tracking constellations designed to counter maneuvering hypersonic threat vectors.
Segmentation Analysis of platforms, technologies, applications, missile types, and defense systems
The market exhibits diverse segmentation dynamics. By platform, it spans land-based, naval, and aerial systems. Technology segments comprise propulsion systems, warhead technology, and guidance systems. Applications cover military, homeland security, and civil defense. Missile categories divide into ballistic, cruise, and anti-ship variants. Defense systems are split into passive solutions—such as decoy systems and hardened shelter systems—and active architectures encompassing fire control systems and interceptor missile systems.
Regional Market Analysis and geographic distribution performance
Geographic performance is heavily skewed toward North America due to outsized defense outlays by the Pentagon and strong domestic innovation hubs. Meanwhile, the Asia-Pacific region demonstrates the fastest relative growth velocity, driven by escalating maritime security tensions and substantial defense budget expansions by nations seeking indigenous missile deterrence and robust coastal defense networks.
In-depth Regional Review of key geopolitical zones
In North America, demand focuses on high-end homeland defense and strategic interceptors developed by firms like General Dynamics Corporation and L3Harris Technologies Inc. Conversely, the Middle East and European theaters prioritize immediate inventory replenishment and counter-UAS integration, boosting specialized contractors like Rafael Advanced Defense Systems Ltd., Israel Aerospace Industries Ltd., and Diehl Defence GmbH & Co. KG.
Company Profiles: Strategic positioning of leading industry participants
Industry leaders maintain distinct competitive moats. RTX Corporation and Lockheed Martin Corporation dominate large-scale integrated air defense primes. Specialty innovators like Kongsberg Defence & Aerospace AS and Saab AB excel in agile command software and naval missile integration. Meanwhile, Asian defense giants such as Mitsubishi Heavy Industries Ltd. and Hanwha Aerospace Co. Ltd. leverage strong domestic government backing to capture expanding regional market share.
Porter's Five Forces Analysis of the sector
The threat of new entrants is remarkably low due to massive capital expenditure requirements, rigorous government certifications, and complex defense IP barriers. Bargaining power of buyers is high, as sovereign defense ministries dictate strict pricing and compliance terms. Supplier power is moderate-to-high for specialized raw materials, while substitute threats remain minimal given the irreplaceable strategic utility of advanced missile systems.
SWOT Analysis of the Missiles And Missile Defense Systems Market
Key strengths include unmatched technological sophistication and deep, long-term government contracts. Weaknesses involve protracted R&D timelines and vulnerability to supply chain shocks. Opportunities abound in directed energy R&D and export-compliant international partnerships. Major threats comprise stringent regulatory compliance delays, budget reallocation risks, and aggressive foreign cyberespionage targeting proprietary defense blueprints.
Value Chain Analysis from raw materials to end-users
The value chain initiates with specialty raw material extraction—such as titanium, carbon fiber, and energetic chemicals. It progresses through subsystem manufacturing by tier-1 suppliers specializing in guidance systems and propulsion systems, culminating in final system integration by primes like BAE Systems plc and Northrop Grumman Corporation before delivery to sovereign military end-users.
Investment Insights and high-potential growth areas
Investors should direct capital toward companies pioneering artificial intelligence for automated threat evaluation, high-energy laser interception technologies, and secure semiconductor supply chains. Firms possessing scalable manufacturing infrastructure capable of meeting surging interceptor volume demands present exceptional upside potential over the 2027 to 2033 forecast horizon.
Conclusion and Key Takeaways for industry stakeholders
The Missiles And Missile Defense Systems Market is transitioning from a period of steady procurement to accelerated, innovation-driven expansion, anchored by a projected market value of 37.14 Billion by 2033. Stakeholders must prioritize technological agility, robust supply chain redundancy, and strategic alignment with allied defense modernization priorities to capture long-term value.
Research Methodology detailing data triangulation and validation
Our baseline estimates and forecasts are meticulously triangulated by cross-referencing public defense budgets, global trade registry data, and proprietary primary interviews with chief technology officers, procurement officers, and defense attachés. Secondary validation leverages macroeconomic indicators, defense think-tank publications, and historical acquisition trends to ensure absolute analytical precision.
Scope of the Report and coverage parameters
This report evaluates the global Missiles And Missile Defense Systems Market industry trends across specified platforms, technologies, applications, missile types, and defense architectures. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include the exclusion of classified black-budget defense programs and unpredictable legislative budget impasses.
Recent Developments in corporate strategy, partnerships, and product launches
Recent market activity is highlighted by strategic joint ventures between European and Israeli defense firms to co-develop advanced multi-layered counter-hypersonic shields. Furthermore, major primes have announced aggressive facility expansions to scale up solid rocket motor production capacity, directly addressing urgent operational demands from international allied militaries.